2026-02-13 12:30:00
INVESTMENT
Is investing better than a loan?
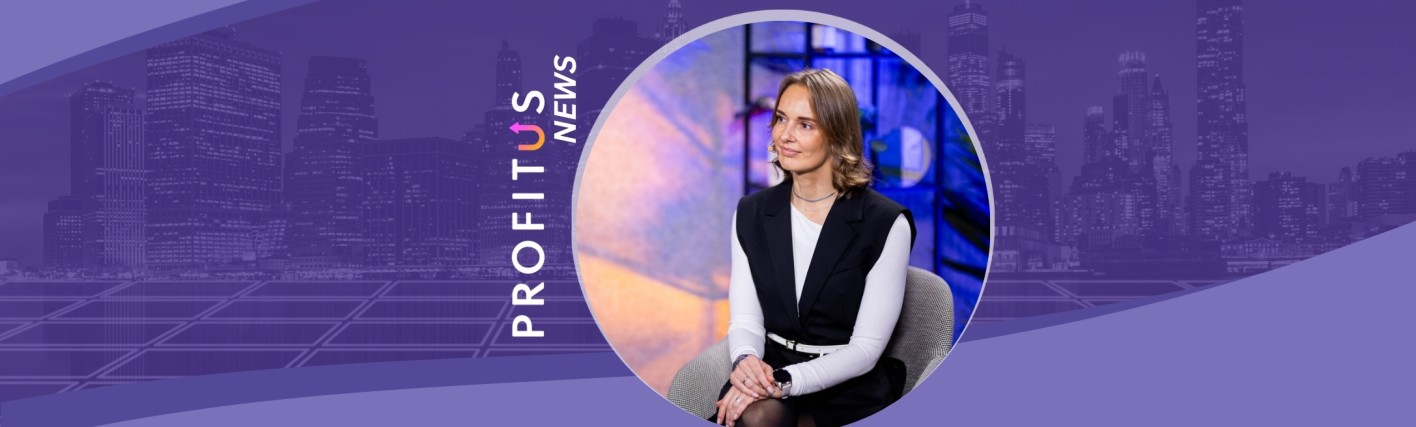
Why are people afraid to invest but not afraid to borrow? Investing is still a topic that residents discuss rather cautiously. However, loans—regardless of their type—are a much more familiar and less controversial subject for Lithuanians. At a conference called “Mano investicija” (“My Investment”), Miglė Grybinienė, marketing manager of the “Profitus” platform and creator of the podcast “Pokalbiai apie pinigus” (“Conversations about Money”), explained the reasons behind this.
False beliefs get in the way
M. Grybinienė notes that Lithuanian residents borrow more than they invest, which is also confirmed by data from the Bank of Lithuania: “According to the latest available data, about 24 percent of households have loans, while only about 6 percent invest.”
However, she believes that hesitation to invest and the activity of borrowing are not driven by fear.
“While preparing for the discussion, to further confirm my idea, I asked a question on my social networks: what causes more stress for people—debt, a loan, or investing? In the end, loans cause more stress, but I believe fewer people invest because they perceive less value in investing than in borrowing. When you borrow, you get value here and now; when you invest, the value comes in the future,” she notes, emphasizing that the immediate benefit we get from borrowing costs more than the benefit we receive in the future through investing.
Doubts about the value of investing are also increased by a lack of control—borrowers see clear interest rates and loan terms, while investing seems uncertain to them: “This is, of course, a matter of knowledge. One should learn more about investing. <...> With a loan, there is often an illusion of control, but unfortunately, there are various circumstances that reduce that control.”
Negative investment stories that reach the public space also discourage Lithuanians from starting to invest. This undermines motivation to engage in such activities.
“What is interesting is that people seem to rely more on stories than on statistics. And we know that people are more inclined to share bad stories and retell them, while good ones—‘I invested, it worked out, as it should have’—are less emphasized. It’s a pity that statistics and positive examples are pushed into the background, rather than the negative stories,” she notes.
She also points out that every financial decision is often emotional and psychological rather than rational, so the negative stories people hear only strengthen doubts and negative emotions: “As one professor said: it is rational only when we count money, but when we make decisions, we often rely on emotions.”
Taking the first step is important
She says the most important thing is the first step—once people dare to make the decision to invest, they begin to see it differently. Therefore, she recommends choosing an amount that, if lost, would not cause noticeable harm, and taking that first step while investing consistently.
“Another very important thing to understand about investing is that it is not some kind of test that you need to pass. It is a consistent, long-term process. When people view investing this way, they are more likely to engage in it. Another mistake is expecting quick results and not realizing that investing should be done gradually, step by step, over a long period,” says M. Grybinienė.
She adds that loans are socially normalized—it seems that everyone has them and they are ordinary, whereas investors are the exception and rarity. However, she is pleased that the situation is gradually changing: “The good news is that the number of people investing is growing very rapidly and almost doubling every year.” Therefore, she also advises surrounding oneself with people who invest and are engaged in this activity.
M. Grybinienė herself says she started investing about 10 years ago. She began her investment journey on a crowdfunding platform, though there are various options, and each person should choose according to their needs. However, the most important thing is to have a vision of what the earned money will be used for.
“I have a vision of a comfortable old age. I want to be able to dine in restaurants, travel, and dress the way I want in old age. So I have that vision of my later life,” she explains.
Her 13-year-old son also invests and has a vision for the future.
“He has been investing for a little over a year. His vision is a car. He is 13 now, and he wants to have a car by the age of 18. I told him that at best I will cover half the cost of the car, and the other half must be his. So now, even the money he receives as gifts, he invests with a very clear goal. That goal really helps people start investing when they visualize the future benefit those funds will bring,” she notes.
Even for those who are not comfortable with mathematics, she says, investing is an excellent way to ensure future well-being.
“Investing is suitable for everyone. And I think not only suitable—it is necessary. You might say you’re not good with numbers, but you receive a salary. You go to the store and buy food or other things. Money is part of your life. So investing should be just as much a part of everyone’s life as all the other places where money is used,” emphasizes M. Grybinienė.
In addition, there are now many tools available to help calculate even the expected return on investments.
“There are calculators online. You can search for, for example, ‘compound interest calculator.’ You may not know how to calculate it yourself. You enter the amount you plan to invest each month, the average return (which platforms usually indicate), and the system calculates how much money you will have after 10 or 15 years. You don’t need to calculate it yourself—the system does it. I highly recommend doing this, because it helps visualize the outcome. It may seem like, say, 100 euros per month is small, but once the system calculates it, the result becomes clear,” she smiles.
Read more: https://www.delfi.lt/projektai/mano-investicija/ar-investavimas-yra-geriau-nei-paskola-120202047